India–Norway commercial freight moves across a focused set of sectors: engineering goods and components feeding Norway’s energy and maritime supply chains, pharmaceutical and chemical products, textiles and garments, processed goods, and project equipment for the offshore and renewables industries. What these shipments share is a dual customs environment with one critical feature that sets Norway apart from a mainland-European destination. India’s export side requires a shipping bill filed on ICEGATE, AD code registration and the right GST treatment — LUT for zero-rated export, or the refund route where appropriate. Norway’s import side is handled by Tolletaten, the Norwegian Customs authority, under Norwegian rules: although Norway is part of the European Economic Area, it is not in the EU customs union, so cargo arriving in Norway is declared and cleared into Norway, not “into Europe.” Seemleius commercial cargo and freight on this corridor is built around getting both ends accurate and consistent with each other.
The India–Norway sea freight corridor
The primary freight route from India to Norway is sea: container vessels from Nhava Sheva (JNPT) and Mundra in western India, and from Chennai Port and Cochin in the south. Few services run direct on the full distance, so most India-origin cargo for Norway tranships at a major North European hub — Hamburg, Bremerhaven or Rotterdam — before a feeder vessel carries it the final leg to Oslo or another Norwegian port such as the container terminals serving the Oslofjord region. Transit times are typically in the range of 30 to 40 days port to port, depending on routing, intermediate calls and the feeder schedule into Norwegian waters. We quote that range honestly rather than presenting the headline port-to-hub figure as if it were the full journey. From the Norwegian port, onward road delivery reaches commercial addresses across the country, on a network where distance, fjord crossings and winter conditions all factor into realistic delivery windows.
Air freight from Mumbai (BOM), Delhi (DEL), Bengaluru (BLR) or Chennai (MAA) into Oslo (OSL), routed through a European hub, covers cargo that cannot wait on sea transit — high-value components, urgent replacement parts for energy and maritime operations, time-sensitive commercial samples and pharmaceutical consignments. We work with you to determine the right mode for each consignment, and we are honest about the cost differential between air and sea.
Indian export documentation
ICEGATE shipping bill, AD code registration, commercial invoice, packing list, certificate of origin and, where relevant, RoDTEP (Remission of Duties and Taxes on Exported Products) and drawback claim handling — so cargo leaves India with clean paperwork and the right export incentive position.
Sea freight to Norwegian ports
Full containers and consolidated groupage from India’s west and south coast ports to Oslo and other Norwegian ports, usually via a North European transhipment hub — typically 30 to 40 days including the feeder leg, with realistic ETAs we will not optimistically shorten.
Norwegian import clearance
Declaration to Tolletaten under Norwegian rules, HS classification, and Norwegian import VAT (merverdiavgift) treatment confirmed before arrival — because Norway’s separate customs regime is exactly where shipments treated as “EU-bound” run into trouble.
Onward delivery and storage
Road delivery from the Norwegian port to any commercial address, transit-document handling for the leg through EU territory, and bonded or temporary storage at the port where duty deferral or pre-clearance staging is required.
Why the EEA-but-not-EU distinction changes the freight plan
For cargo moving from India to a mainland-EU country, the goods cross one external customs frontier and then move freely. For cargo bound for Norway, there is an additional consideration: if the routing takes the shipment through EU territory before it reaches Norway, the leg through the EU is handled under transit procedures, and the substantive import declaration is made to Tolletaten when the goods reach Norway. The HS code assigned in the Indian shipping bill drives the duty and VAT treatment Tolletaten applies, and a misclassification at the India end produces a discrepancy at the Norwegian import stage that causes delays and back-duty exposure. We confirm classification and the Norwegian VAT position before the shipping bill is filed. Origin documentation also matters, and it is widely misunderstood on this lane: the EEA Agreement governs trade between the EU and the EEA states and does nothing for Indian-origin goods, so the instrument that shapes preferential duty between India and Norway is the India–EFTA Trade and Economic Partnership Agreement (TEPA) signed in March 2024 — and getting the origin declaration right under it protects the duty position your finance team has priced into the contract.
Indian export sectors we work with on the Norway corridor
- Engineering goods and industrial components — feeding Norway’s offshore energy, subsea and maritime supply chains from Pune, Chennai and India’s industrial clusters
- Pharmaceuticals and active pharmaceutical ingredients — handled with the temperature, documentation and regulatory care the Norwegian market requires
- Textiles, garments and apparel — from Ahmedabad, Surat and Tirupur, coordinated with Norwegian importers and distribution partners
- Chemical and dyestuff exports from Gujarat — with hazardous-goods (IMDG) classification, MSDS handling and the documentation the sea route requires
- Project and renewable-energy cargo — equipment for wind, hydro-adjacent and offshore projects, including oversized and out-of-gauge handling
- Exhibition and temporary-import material — including ATA carnet handling for trade fairs and industry events in Oslo and other Norwegian cities
How a commercial shipment runs
- Brief us. Cargo description, HS code if known, value, weight and dimensions, origin in India, applicable GST/LUT treatment, RoDTEP eligibility, and the required arrival date in Norway.
- Quote and route. A clear freight quote with mode, realistic transit time including any transhipment and feeder leg, and the Indian export and Norwegian import documentation treatment explained — including transit handling for any EU leg and storage staging where it benefits you.
- Document and book. ICEGATE shipping bill and export paperwork filed; Tolletaten import documentation prepared; space booked and cargo collected from the India origin.
- Monitor and clear. Your coordinator tracks the shipment through transit and the Norwegian port process, manages Tolletaten import clearance, and confirms delivery at the Norwegian destination.
The same documentation rigour applies whether you are sending a single consignment or running a recurring programme into Norway, and our country overview on moving from India to Norway sets the wider context. Request a freight quote and we will confirm the right approach for your cargo, your timeline and your compliance requirements.
Norwegian import VAT, and how it actually falls on the importer
The rate to plan around is 25 per cent MVA on most goods, with a reduced rate on foodstuffs and lower rates again on passenger transport and accommodation. The mechanism matters more than the rate. A consignee entered in the Norwegian VAT register does not normally pay import VAT at the frontier: the amount is calculated and reported on that business’s own periodic VAT return and deducted in the same return where the goods feed a taxable activity, so the cash effect is close to neutral. A consignee that is not VAT-registered in Norway has no such route, and the VAT falls due at clearance as a real cost. That single distinction decides whether an India to Norway consignment lands with a manageable customs bill or an unbudgeted one, and it is settled by whose organisation number appears as importer on the declaration — a decision taken weeks before the vessel sails, not at the quay.
The taxable base is the customs value together with any duty and the freight and insurance to the Norwegian frontier, which means the transhipment and feeder legs sit inside the base. Finance teams pricing from an FOB invoice are regularly caught by that. Where a Norwegian buyer is importer of record, agree in writing whose organisation number goes on the declaration before space is booked. Where an Indian exporter wants to import in its own name, a Norwegian VAT representative arrangement is the usual route and it takes time to establish, so it belongs at the start of a programme rather than in the week the container arrives.
Preferential origin runs through the India–EFTA agreement, not the EEA
Because Norway is not an EU member state, EU trade preferences have no bearing on Indian-origin goods arriving there. The instrument that governs preferential duty between India and Norway is the India–EFTA Trade and Economic Partnership Agreement, signed in March 2024 between India and the four EFTA states — Iceland, Liechtenstein, Norway and Switzerland. Whether a particular consignment benefits turns on the tariff line, on the product satisfying the agreement’s origin rules, and on a valid origin declaration travelling with the goods.
Two practical consequences follow. Confirm the current rate for your HS code against the Norwegian tariff before quoting a landed price to a customer, because industrial tariffs into Norway are low or nil on many lines with or without preference, and a preference claimed but not substantiated is more expensive than one never claimed. And keep the origin evidence filed against the shipment — supplier declarations, bills of materials, production records — since it is asked for after clearance far more often than at it.
The document set that travels with an India to Norway consignment
| Document | Prepared at | What it does at the Norwegian end |
|---|---|---|
| Shipping bill, filed on ICEGATE | India | Fixes the classification and declared value that Tolletaten compares against the import declaration |
| Commercial invoice and packing list | India | Forms the basis of the Norwegian customs value; line descriptions must match the goods rather than summarise them |
| Bill of lading or air waybill | Carrier | Establishes the consignee and controls release at the Norwegian port or airport |
| Origin declaration | Exporter | Supports a preferential claim under the India–EFTA agreement where the line qualifies |
| Transit declaration for the EU leg | Transhipment hub | Carries the goods across EU territory without creating an EU import |
| IMDG paperwork and safety data sheet | India | Required for chemicals, dyestuffs and any classified dangerous goods on the sea leg |
| Advance digital notification of arrival | Carrier or declarant | Tolletaten expects the data lodged electronically ahead of the goods rather than at the border |
Which Norwegian port suits which cargo
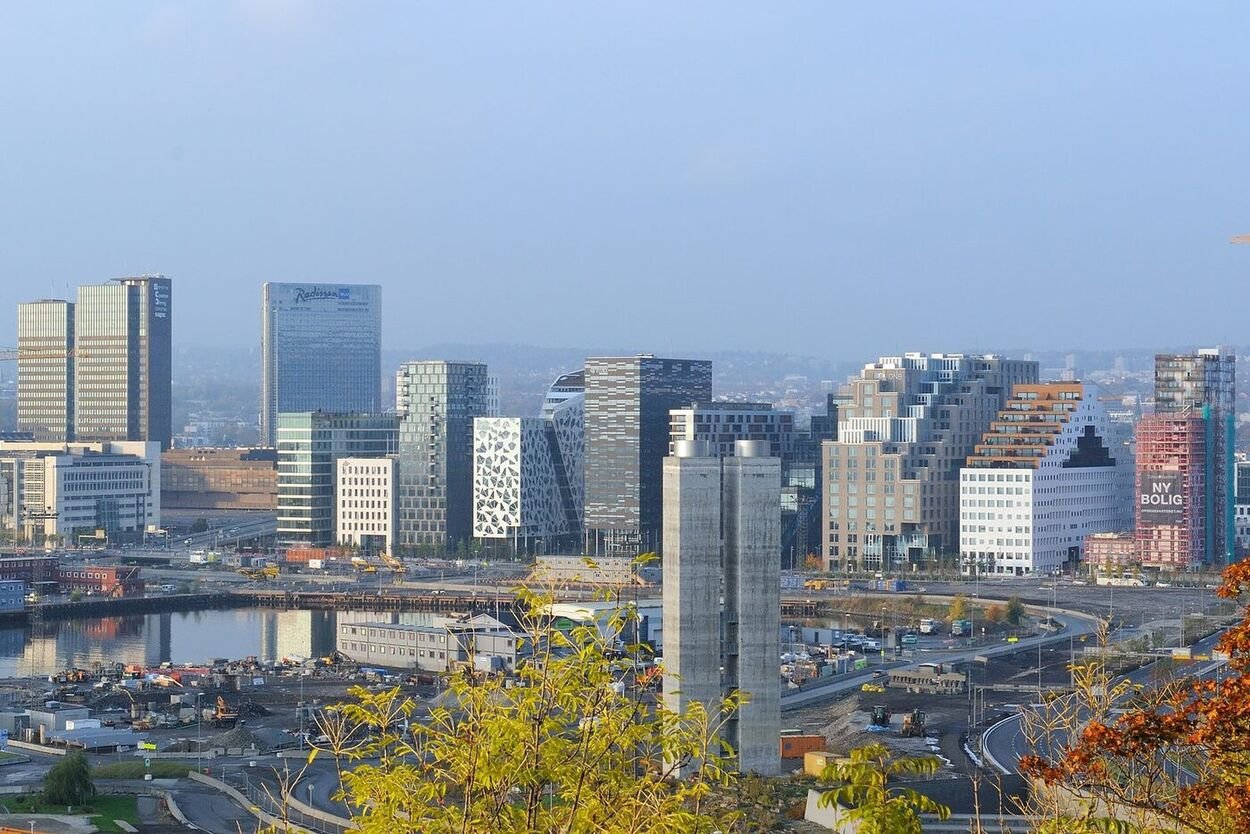
Oslo is the natural discharge point for cargo destined for the capital region and the eastern interior, and it takes the largest share of feeder volume. Larvik and Borg in the outer Oslofjord frequently work out better for industrial consignees in Vestfold and Østfold, and they are less congested. Kristiansand at the southern tip is useful for Agder and as a road hub. Stavanger, through the Risavika terminal, is the port to aim at for anything feeding the Rogaland energy cluster, and Bergen serves the western maritime industry and the fjord region behind it. Ålesund handles Sunnmøre and its shipbuilding and fishing-technology base; Trondheim serves Trøndelag. For northern Norway, rail through Sweden to Narvik or a coastal service is often quicker and cheaper than road from an Oslofjord port, and it is worth pricing both before defaulting to the capital.
When air freight earns its cost on this lane
Air from BOM, DEL, BLR or MAA into Oslo (OSL) — and less often into Bergen (BGO), Stavanger (SVG) or Trondheim (TRD) — routes through a European hub, and it is a rational choice in a narrow set of cases. Spares for an offshore installation or a vessel where the operational day rate dwarfs any freight bill. Temperature-controlled pharmaceutical consignments where the sea leg introduces too much exposure. Launch quantities and commercial samples where the market entry date is contractual. Outside those, the arithmetic on this corridor favours sea decisively, and a mixed approach often serves better than either extreme: the critical fraction by air to hold the schedule, the balance by sea behind it.
Seasonality that affects an India to Norway freight programme
Three seasonal effects are worth building into a planning calendar. The south-west monsoon affects working conditions and yard turnaround at India’s west-coast ports between roughly June and September, which shows up as slippage rather than closure. North Sea winter weather from November through February disrupts feeder schedules into Norwegian ports more than it disrupts the deep-sea leg, so the last few hundred kilometres are where the schedule risk concentrates. And Norway itself effectively pauses twice a year — the week around Easter and the July holiday weeks, when receiving departments run on skeleton staff and a container delivered to a closed goods entrance still incurs demurrage. Booking around those windows is cheaper than working through them.
Common questions from Norwegian-bound shippers
Can one bill of lading cover a delivery beyond the Norwegian port?
Yes, on a through arrangement, but the import declaration into Norway still has to be made in someone’s name and the onward road leg is a separate cost line. Ask for the quote broken out — deep sea, feeder, terminal handling, clearance, delivery — so that a comparison between offers is a real comparison.
Do exhibition goods have to be imported permanently?
No. Norway accepts ATA carnets, which is the usual mechanism for equipment travelling to a trade fair in Oslo or Stavanger and returning to India afterwards. The carnet must be raised in India before departure; it cannot be arranged retrospectively once the goods are in a Norwegian warehouse.
What most often delays a consignment at the Norwegian end?
A mismatch between the ICEGATE shipping bill and the Norwegian import declaration — a different classification, a value that does not reconcile, or a packing list that describes cartons rather than contents. It is a paperwork failure with a physical cost, and it is entirely avoidable by preparing both declarations from one verified data set.
Is bonded storage available at the Norwegian port?
Temporary storage is available at the main terminals and is useful where a consignee’s VAT registration or a customer’s site readiness is still being finalised. It is time-limited and priced by the day, so it works as a bridge across a short gap and not as a warehousing strategy.